
Every cashback headline in India sounds like free money until you read the monthly cap — the line that turns “5% on everything” into “5% up to ₹X, then zero.”
If you searched best cashback card India 2026, you want one answer: which card actually returns the most rupees for your bills, apps, and malls — not a generic top-five poster.
Below we compare six mainstream cashback cards using issuer-facing numbers on CardCheck (snapshot 2026-05-20). We show effective rates after caps, a pick-by-spend matrix, and where to model your own basket in the Rewards calculator.
Rule of thumb: the “best” card is the one whose published rate stack matches where you already spend — then you pay in full every month so interest never eats the cashback.
Cards in this comparison (6)
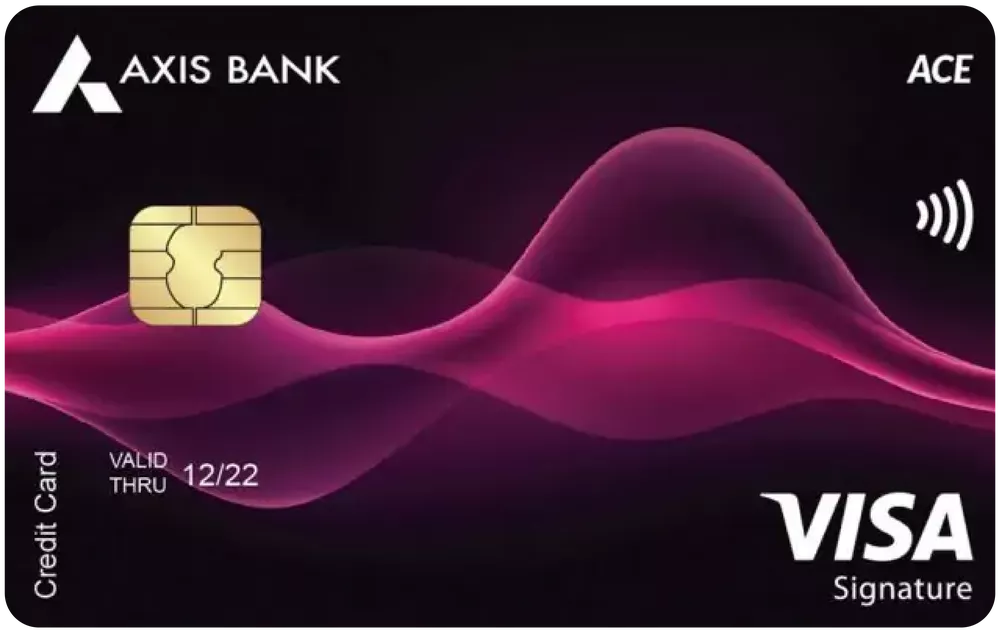
ACE Credit Card
Cashback on utility bills via Google Pay and daily spending
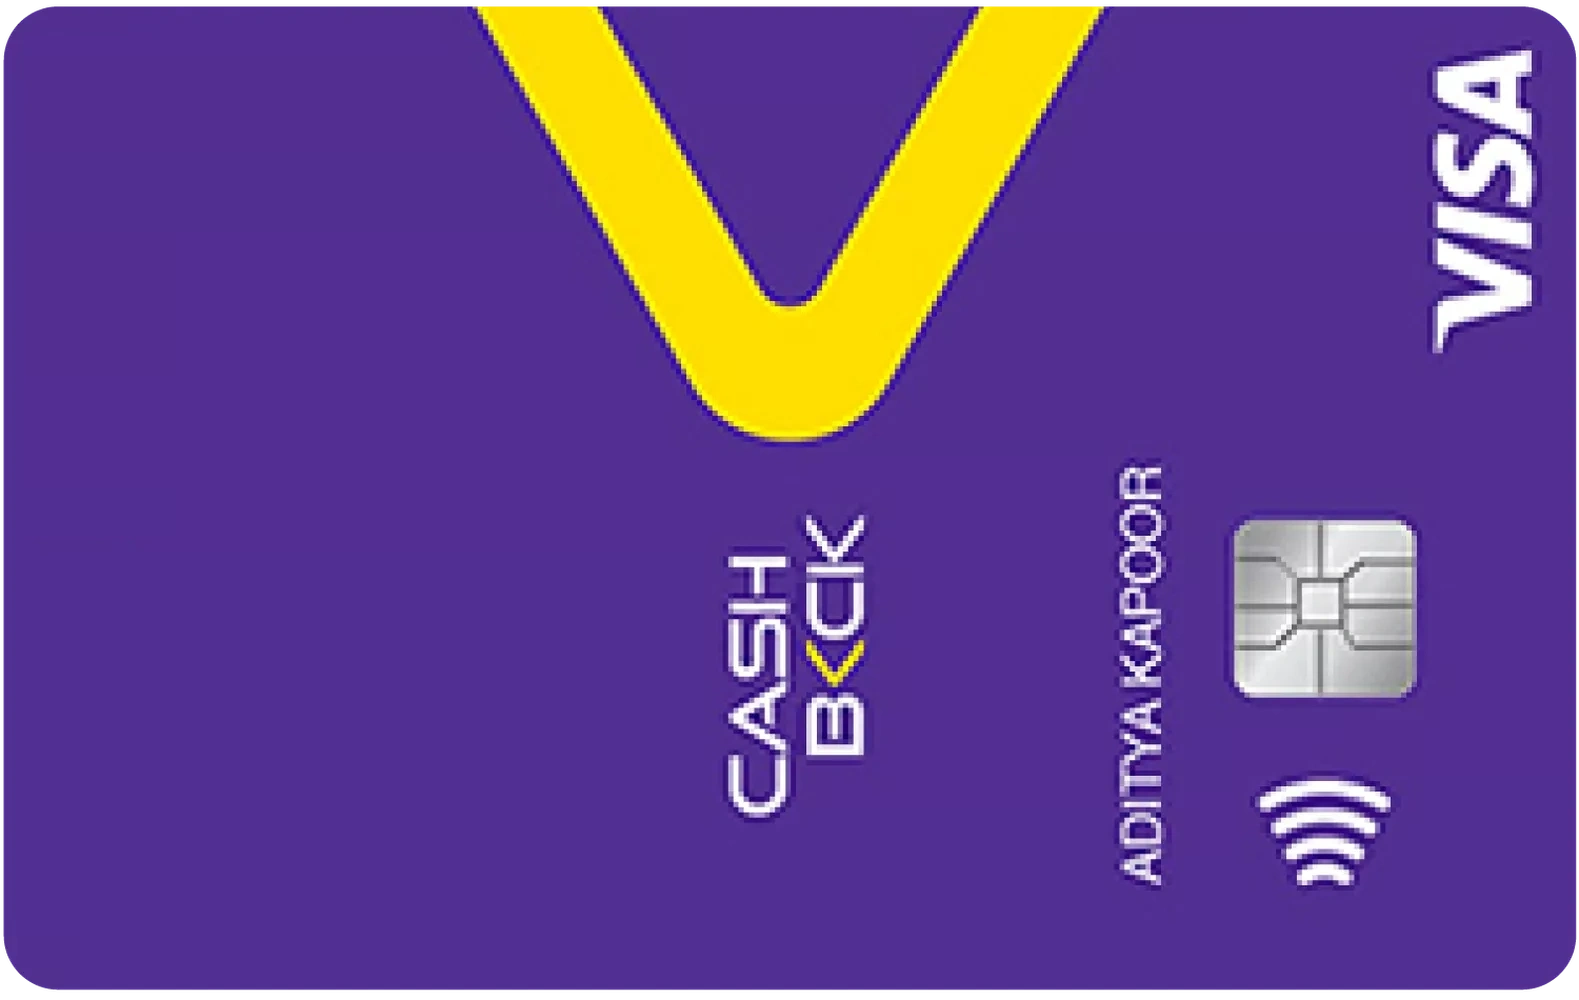

CASHBACK SBI Card
Online cashback
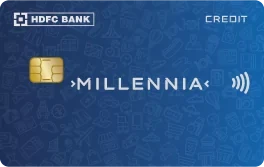

HDFC Millennia Credit Card
online shoppers
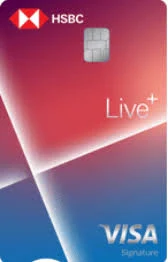

HSBC Live+ Credit Card
Food delivery & dining — 10% cashback on Swiggy, Zomato & restaurants
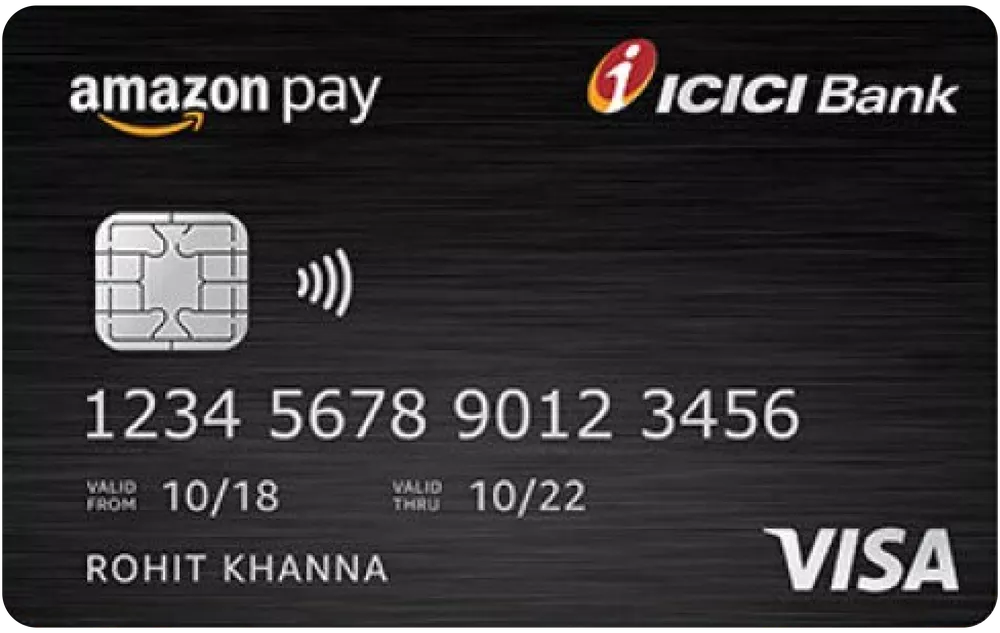
Amazon Pay ICICI Bank Credit Card
Rewards on Amazon Purchases
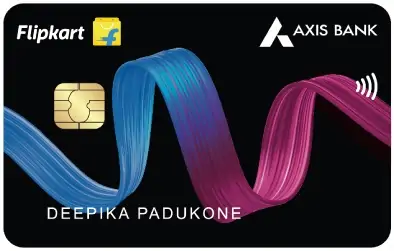
Flipkart Axis Bank Credit Card
Flipkart and online shopping
How cashback works on Indian credit cards (2026)
Statement credit — cashback reduces your bill (SBI Cashback, Axis Ace, HSBC Live+). Cleanest for salaried users who want rupees back without wallet lock-in.
Wallet / points — Amazon Pay ICICI credits Amazon Pay balance; HDFC Millennia pays CashPoints you redeem against the statement (often quarterly). Still real value, extra friction.
Caps beat headlines. A 10% rate with a ₹1,000/month cap is a 10%-up-to-₹10,000 category card — not 10% on ₹50,000 of groceries.
Confirm exclusions in each bank’s Most Important Terms and Conditions (MITC) — fuel, rent, wallet loads, EMI, and government payments are commonly excluded.
Best cashback card by spend type (quick picks)
| Your dominant spend | Best fit (2026 snapshot) | Why |
|---|---|---|
| Household bills via Google Pay | Axis Bank ACE Credit Card | 5% on GPay utility/recharge (capped ₹500/month on that bucket); 4% on Swiggy/Zomato-style apps |
| Any online merchant | CASHBACK SBI Card | Flat 5% online, 1% offline; cashback to statement |
| Amazon.in (Prime) | Amazon Pay ICICI Bank Credit Card | 5% on Amazon for Prime (3% non-Prime); lifetime free |
| Flipkart / Myntra | Flipkart Axis Bank Credit Card | 5% on Flipkart + Myntra in published stack |
| Listed e-commerce partners | HDFC Bank Millennia Credit Card | 5% CashBack on Amazon, Flipkart, Swiggy, etc. (partner list only) |
| Dining + delivery + groceries | HSBC Live+ Credit Card | 10% on dining, Swiggy, Zomato, groceries, entertainment — capped ₹1,000/month combined |
Two cards often beat one: specialist + generalist (e.g. Ace for bills + SBI for random online).
Top cashback cards reviewed
Axis Bank ACE Credit Card
Fees: joining ₹499, annual ₹499 — waived on ₹2 lakh annual spend (issuer disclosure).
Earn: 5% on utility/recharge via Google Pay (cap ₹500/month on that line), 4% on Swiggy, Zomato, BigBasket, Ola, Hotstar, Zee5, 1.5% on other retail with no blanket monthly cap on base spend in our catalog.
Who it suits: Rent-paying households that route electricity, broadband, mobile through GPay. Less ideal if Amazon/Flipkart dominate and you never touch GPay bills.
CASHBACK SBI Card
Fees: ₹999 joining + annual — waived on ₹2 lakh annual spend.
Earn: 5% on all online purchases (any merchant), capped at ₹5,000 cashback/month in our snapshot (~₹1 lakh online spend at 5%). 1% offline.
Catch: SBI and other issuers periodically tighten cashback rules — after major programme changes, re-read SBI Card MITC and our SBI reward cap explainer before you count on old caps.
Amazon Pay ICICI Bank Credit Card
Fees: ₹0 joining and annual (lifetime free in issuer copy).
Earn: 5% on Amazon.in for Prime members, 3% for non-Prime, 2% on Amazon Pay partner merchants, 1% elsewhere. Cashback lands in Amazon Pay balance.
Who it suits: Prime members with heavy Amazon carts — unbeatable fee ROI as a second card even when SBI wins generic online.
Flipkart Axis Bank Credit Card
Fees: ₹500 joining + annual — waiver commonly tied to ₹2 lakh annual spend (confirm on Axis Flipkart page).
Earn: 5% on Flipkart and Myntra, elevated rates on listed partners, 1.5% base elsewhere in catalogue summaries.
Who it suits: Myntra wardrobe + Big Billion Day spend — pair with a non-co-brand card for everything outside the Axis partner list.
HDFC Bank Millennia Credit Card
Fees: ₹1,000 — waived on ₹1 lakh annual spend (lower waiver bar than ₹2L peers).
Earn: 5% CashBack only on named partners (Amazon, Flipkart, Myntra, Swiggy, Zomato, Uber, BookMyShow, etc.). 1% on other retail. CashBack posts as CashPoints, quarterly in issuer copy.
Who it suits: Young salaried spenders living inside HDFC’s partner mall — frustrating if your favourite store is not on the list.
HSBC Live+ Credit Card
Fees: ₹999 — waived on ₹2 lakh annual spend.
Earn: 10% on dining, Swiggy, Zomato, groceries, entertainment — ₹1,000/month cap across those accelerated categories combined. 1.5% on other eligible retail.
Who it suits: Urban households spending ₹8,000–₹10,000/month on food + grocery delivery — fee can recover in one strong month.
Comparison table — fees, best rate, caps
| Card | Annual fee | Best published rate | Category | Monthly cap (snapshot) | Credit type |
|---|---|---|---|---|---|
| ₹499 | 5% | GPay utilities | ₹500 on 5% bucket | Statement | |
| ₹999 | 5% | All online | ₹5,000 cashback | Statement | |
| ₹0 | 5% (Prime) | Amazon.in | No monthly cap in catalogue | Amazon Pay | |
| ₹500 | 5% | Flipkart / Myntra | Per MITC | Statement | |
| ₹1,000 | 5% | Partner platforms only | Partner rules in MITC | CashPoints | |
| ₹999 | 10% | Food + grocery + dining | ₹1,000 on 10% bucket | Statement |
Use Compare to line these up on fees, forex markup, and lounge access if travel matters too.
Effective cashback after caps (worked examples)
Illustrative only — assumes eligible MCC coding and full payment of bills.
₹12,000/month online shopping (mixed apps):
- SBI Cashback: 5% × ₹12,000 = ₹600 back (under ₹5,000 cap).
- Millennia: only partner-tagged spend earns 5%; rest at 1%.
₹6,000/month Swiggy + Zomato + BigBasket:
- HSBC Live+: 10% × ₹6,000 = ₹600 (under ₹1,000 cap).
- Axis ACE: 4% × ₹6,000 = ₹240 on those apps.
₹4,000/month electricity + mobile via GPay:
- Axis ACE: 5% × ₹4,000 = ₹200 (under ₹500 utility cap).
Plug your real split into the Rewards calculator — caps and category tags change the winner fast.
What cashback cards usually exclude
Across the cards above, issuers commonly exclude or downgrade:
- Fuel — often surcharge waiver only, not accelerated cashback.
- Rent via aggregators — frequently coded out of earn.
- Wallet loading and some government payments.
- EMI conversions and international spends (plus 3–3.5% forex markup).
Before you optimise rent or tuition, open the card’s MITC PDF on the issuer site — not a blog table.
Verdict: one card or a small stack?
Single-card minimalist: CASHBACK SBI Card if most spend is online and you will hit fee waiver at ₹2 lakh/year.
Bill + delivery household: Axis ACE + optional HSBC Live+ if food delivery exceeds ₹8k/month.
Platform loyalist: co-brand (Amazon Pay ICICI or Flipkart Axis) for the mall, SBI or Ace for everything else.
Still torn? The Card match quiz takes about a minute and maps spend habits to catalogue picks — then rerun the calculator with your numbers.
FAQ
- Which is the best cashback credit card in India in 2026?
There is no universal winner. HSBC Live+ leads on food and grocery delivery (10% with a ₹1,000/month cap). SBI Cashback leads on uncategorised online spend (5% with a ₹5,000/month cap in our snapshot). Axis ACE leads on GPay utility bills. Match the card to your spend mix.
- Is Axis ACE better than SBI Cashback?
ACE wins when you pay utilities through Google Pay and use its 4% partner apps heavily. SBI wins when you shop on many different websites without caring which platform — flat 5% online is simpler. Model both in the Rewards calculator.
- Is Amazon Pay ICICI the best free cashback card?
For Prime members with heavy Amazon.in spend, the ₹0 fee and 5% headline are hard to beat. Outside Amazon, 1% base is modest — treat it as a specialist, not your only card.
- Do cashback cards give money in my bank account?
Rarely. Most credit statement cashback or wallet balances. HDFC Millennia uses CashPoints you redeem against the card bill. None of these replace a salary credit.
- How much spend do I need to waive the annual fee?
Examples from our snapshot: ₹2 lakh/year for SBI Cashback, Axis ACE, and HSBC Live+; ₹1 lakh/year for HDFC Millennia. Miss the threshold and net cashback drops by the fee amount.
- Can I use a cashback card for international travel?
You can swipe, but forex markup (~3.5%) usually wipes out domestic cashback maths. Carry a low-forex card for trips; keep cashback cards for India spends.
Cards in this comparison (6)
ACE Credit Card
Cashback on utility bills via Google Pay and daily spending
CASHBACK SBI Card
Online cashback
HDFC Millennia Credit Card
online shoppers
HSBC Live+ Credit Card
Food delivery & dining — 10% cashback on Swiggy, Zomato & restaurants
Amazon Pay ICICI Bank Credit Card
Rewards on Amazon Purchases
Flipkart Axis Bank Credit Card
Flipkart and online shopping
Vineet Verma
Lead AnalystLead Financial Researcher & Credit Card Analyst at CardCheck
Vineet specializes in Indian retail banking terms, reward point economics, and MITC verification. Every insight is audited against official bank filings.